An unexpected bill can arrive long before your next salary. For an S Pass holder supporting a household locally and family overseas, that timing can create a difficult choice: use savings, delay another expense or consider financing.
Before comparing S Pass loans in Singapore, understand what determines eligibility, which records support an application and how borrowing limits work. A valid employment pass opens the possibility of assessment; it does not promise approval.
We believe the most useful starting question is simple: will the proposed instalment fit your budget after essential commitments? That answer matters more than how quickly funds might become available.
Eligibility: What An S Pass Holder Needs To Demonstrate
An S Pass holder residing in Singapore can apply for financing from a regulated moneylender. Assessment focuses on valid residency status, verifiable earnings, existing obligations and repayment ability. Providers may set their own acceptance criteria within the legal framework, so meeting basic conditions does not guarantee an offer.
At Khalon & Gill, we accept applications from adults aged 21 or above with a valid work pass and steady income. Our foreigner financing service involves reviewing supporting evidence and affordability before deciding whether an arrangement is suitable.
Employment circumstances also deserve attention. If your contract ends soon, your pass is approaching expiry or you have recently changed jobs, explain the situation early. Ask whether further confirmation is needed rather than assuming every provider follows an identical policy.
When comparing personal loans in Singapore for foreigners, distinguish between banks and moneylenders. Their product requirements and lending frameworks differ. The limits discussed below concern unsecured credit from moneylenders, where no asset is pledged as security.
Finally, review your own monthly position. Include rent, transport, food, family remittances and existing debt payments. A repayment plan that depends on uncertain overtime or an expected bonus leaves little room for disruption. If normal earnings cannot cover it comfortably, reduce the request or reconsider whether borrowing is appropriate.
Documents: Provide Accurate, Verifiable Information
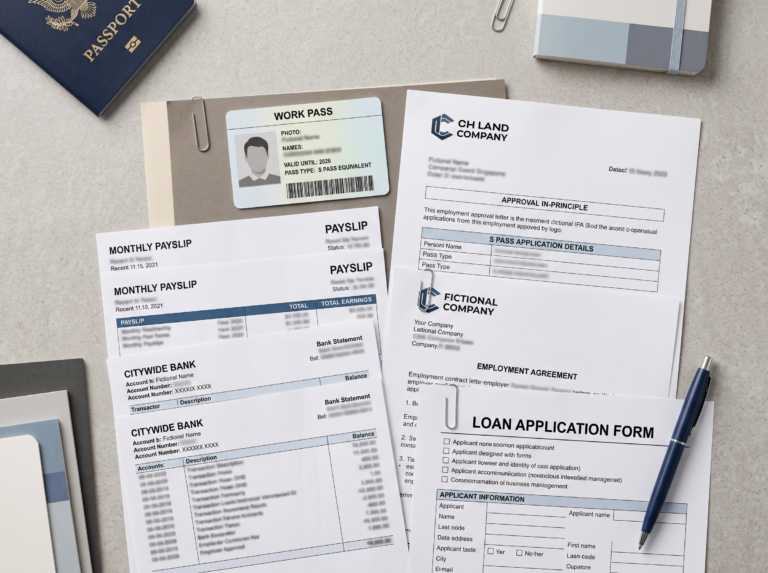
Once the basic conditions are clear, prepare records that establish identity, employment and your current address. Complete paperwork helps an officer assess the request accurately, although it cannot remove the need for verification.
The usual checklist includes:
-
Valid S Pass & time to expiry
These establish identity and immigration status. Check that personal details match the application and there is at least more than 6 months to expiry.
-
Recent payslips
Prepare the latest three months when requested. They help demonstrate regular earnings and identify changes in salary.
-
Salary-crediting bank statements
These may support payslips by showing when wages actually reached your account.
-
Employment confirmation
A contract or employer’s letter may clarify your role, start date and pay, particularly following a recent job change.
-
Residential evidence
A tenancy agreement, utility bill or bank statement may help confirm your Singapore address, subject to acceptance.
-
Existing financial details
Prepare information about current financial commitments and due dates so the affordability review reflects your actual commitments.
At Khalon & Gill, we request valid work-pass information, residential proof and income or employment evidence from foreign applicants. Confirm the exact checklist with us before visiting, especially if your salary records cover only a short period.
Check for inconsistencies before submission. An old address, different name format or unexplained salary variation can prompt additional questions. Provide truthful explanations and current supporting evidence rather than altering records to make them appear consistent.
Keep control of sensitive information throughout. Never disclose Singpass passwords, banking credentials or one-time passwords. A moneylender must not retain your passport or other original identification.
Applications may begin online, but legal moneylenders in Singapore always conduct face-to-face identity verification at their approved premises before granting credit. Read the agreement, have unfamiliar terms explained in a language you understand and obtain a copy before leaving.
Borrowing Limits: Calculate The Ceiling And The Cost
For foreigners with an annual income of S$40,000 and above, the next step is understanding the statutory maximum. Foreigners residing locally, unsecured borrowing is capped as follows:
| Annual income | Maximum across all licensed moneylenders combined |
|---|---|
| Below S$10,000 | S$500 |
| S$10,000 to S$20,000 | S$3,000 |
| S$20,000 and above | Six times monthly income |
These are shared limits, rather than separate allowances for each provider. For example, assessed monthly earnings of S$4,000 produce a S$24,000 ceiling. Existing unsecured principal of S$9,000 would leave theoretical headroom of S$15,000, subject to assessment.
The Moneylenders Credit Bureau enables licensed moneylenders in Singapore to review a borrower’s existing loans. Available headroom does not mean that the full balance will be approved or affordable.
Costs require a separate review. Interest is capped at 4% monthly on outstanding principal. An upfront administrative fee cannot exceed 10% of the principal. Late interest is limited to 4% monthly on overdue amounts, while late fees cannot exceed S$60 for each month of delay.
Qualifying unsecured, non-business loans disbursed from 15 September 2026 come with an added safeguard: three business days to reconsider and cancel at a reduced cost. No interest is charged when the cancellation requirements are met, although a permitted portion of the approval fee may be retained.
Conclusion: Apply With A Clear Repayment Plan
Understanding S Pass loans in Singapore means connecting eligibility, reliable evidence and realistic instalments. The legal maximum should guide your checks, while your budget guides your decision.
Contact Khalon & Gill through our official website to discuss our foreigner loan service and arrange an assessment at our physical office. We will explain the required paperwork, applicable charges and repayment terms so you can make an informed decision before committing.
